- Home
- Credit Score
- Check HDFC Bank CIBIL Score
HDFC Bank CIBIL Score: How to Check and Improve Your HDFC CIBIL Score
The Credit Information Bureau India’s CIBIL Score is an important metric in India’s financial landscape that acts as a financial report card, summarising an individual’s creditworthiness. Ranging from 300 to 900, this three-digit score reflects a person’s credit history and repayment behavior, playing a crucial role in their eligibility for various financial products, including credit cards, personal loans, and home loans. HDFC Bank, a leading name in the Indian private banking sector.

- Instant Results
- No Hidden Fees
- Secure & Confidential
- No Impact on Your Credit Report
I agree to the Terms and Conditions of TUCIBIL and hereby provide explicit consent to share my Credit Information with Urban Money Private Limited.
Verify your number
Enter 6 Digit OTP
Change mobile number
Table of Content
How to Check Your HDFC CIBIL Score?
Awareness of the HDFC CIBIL score is important for responsible financial management. HDFC Bank, in collaboration with CIBIL, offers convenient methods for customers to check their scores. Here is a step-by-step guide:
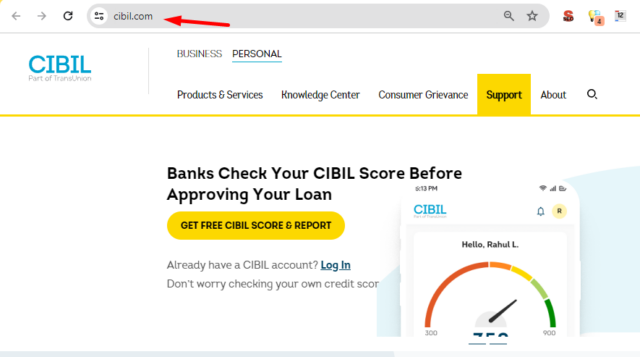
- Visit the official CIBIL website (www.CIBIL.com).
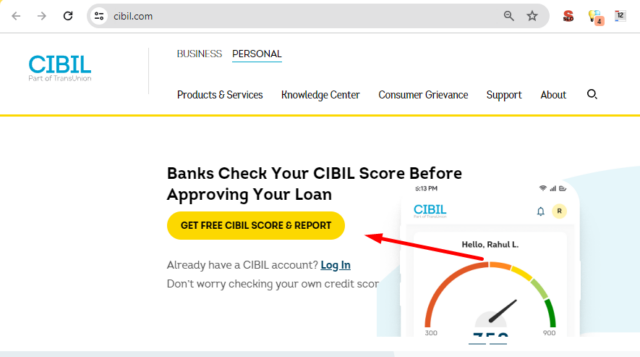
- Locate the “Get Your CIBIL Score” section.
- Fill out the online application form with your personal details, including your full name, date of birth, and PAN number.
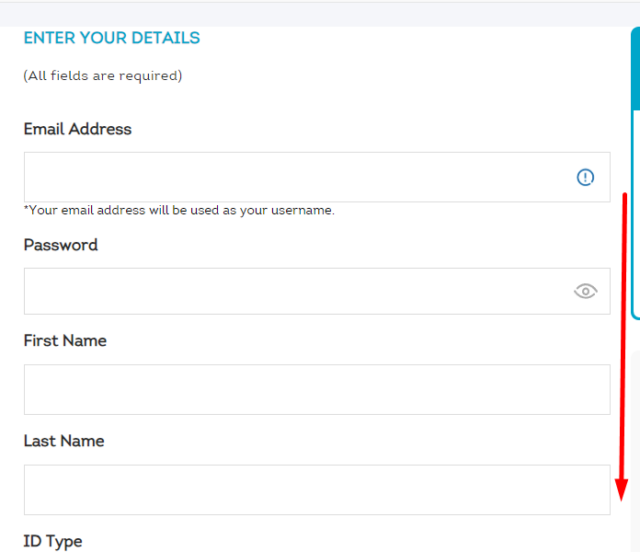
- Answer questions about your credit history, such as the number of credit cards you possess and any loans you have taken.
- Submit the form and pay the nominal fee associated with the credit report.
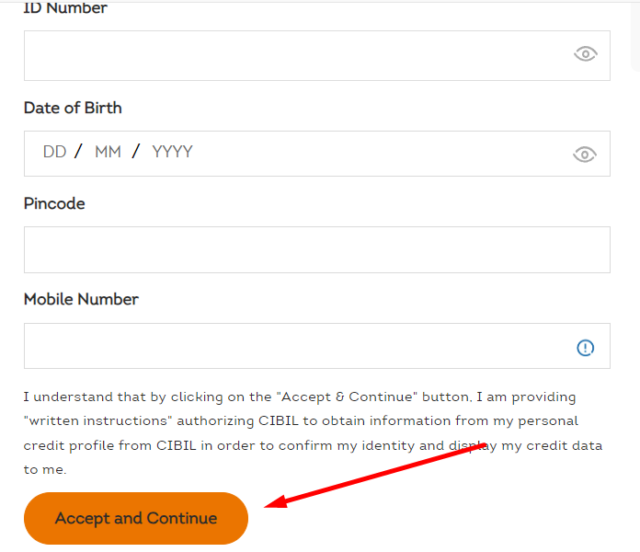
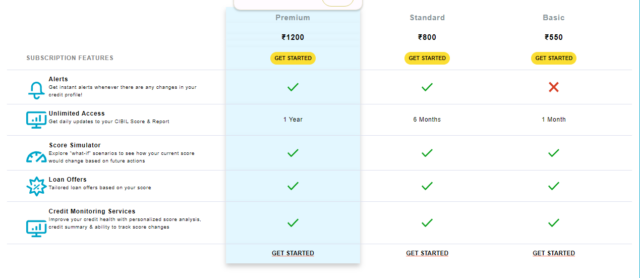
Upon successful submission, you will receive your CIBIL Score report, which details your credit history, repayment behavior, and factors influencing your score. Regularly monitoring your CIBIL Score helps you identify potential issues and take corrective action to improve it.
Role of CIBIL Score in Securing an HDFC Bank Credit Card
Obtaining an HDFC Bank credit card necessitates meeting specific HDFC CIBIL score requirements. Generally, a score closer to 900 is considered excellent and significantly increases the likelihood of credit card approval. However, a score of 700 to 749 is often considered the minimum threshold for HDFC Bank credit cards. This score assures the bank of the applicant’s responsible credit management and reduces lending risk. While individuals with scores below 650 may still be eligible for certain cards, they might face higher interest rates, lower credit limits, or stricter eligibility criteria. It is important to note that the specific score requirement can vary depending on the type of HDFC Bank credit card being applied for. Premium cards with exclusive benefits often require a higher CIBIL score than standard cards. Additionally, certain specialized cards for students or individuals with limited credit history may have slightly lower score requirements. Maintaining a good CIBIL score is crucial for securing favorable terms and conditions on any HDFC Bank credit card, maximizing benefits, and minimizing potential downsides of credit card use.
Eligibility Criteria for HDFC Bank Credit Cards
Beyond the HDFC CIBIL score, additional eligibility criteria must be met to qualify for an HDFC Bank credit card. These factors include:
- Residency: Applicants must be Indian residents.
- Age: The minimum age requirement typically ranges between 21 and 25, depending on the specific card. The upper age limit is usually 65.
- Income Stability: A stable income source meeting the minimum threshold for the card type is mandatory. Income documents, such as salary slips or income tax returns, are required for verification.
- Employment Status: Salaried individuals, self-employed professionals, and individuals with agricultural income may be eligible, depending on the card and their income stability.
Factors Affecting HDFC CIBIL Score
Several factors influence the HDFC CIBIL score; here are some key elements:
- Repayment History: Timely payments of EMIs, credit card bills, and other loans significantly improve the CIBIL Score. On the other hand, late payments, defaults, or write-offs negatively impact your score.
- Credit Utilization Ratio: This ratio measures the amount of credit you use relative to your credit limit. Ideally, maintaining a utilization ratio below 30% demonstrates responsible credit management and positively impacts your score.
- A mix of secured and unsecured loans: A healthy mix of secured loans, such as home loans, and unsecured loans, like credit cards, indicates responsible credit behavior and can improve your score.
- Length of Credit History: A longer credit history with a consistent track record of on-time payments strengthens the CIBIL Score. On the other hand, a limited or nonexistent credit history can make it challenging to obtain a high score.
- Hard Inquiries: Every time you apply for a new loan or credit card, a “hard inquiry” is registered on your credit report, which can slightly lower your score. Limiting frequent applications can help maintain a good score.
Range Table for HDFC CIBIL Score
Here is the range table for HDFC CIBIL scores for quick reference. This table categorizes credit scores used by HDFC and other financial institutions. A higher CIBIL score indicates better creditworthiness, which can be beneficial when applying for loans or credit cards.
| CIBIL Score Range | Credit Quality |
| 300 – 549 | Poor Credit |
| 550 – 649 | Fair Credit |
| 650 – 699 | Good Credit |
| 700 – 749 | Very Good Credit |
| 750 – 900 | Excellent Credit |
How Can the Low Credit Score of HDFC Bank be Improved?
A low HDFC CIBIL score is not irreversible. By adopting responsible financial practices, you can improve your score over time and increase your chances of obtaining an HDFC Bank credit card. Here are some effective strategies:
- Make Timely Payments: Ensure on-time payments for all your EMIs, credit card bills, and other loans. Even a single missed payment can significantly damage your score.
- Maintain Low Credit Utilization: Keep your credit card balances low and avoid exceeding your credit limit. Ideally, aim for a utilization ratio below 30%.
- Build a Positive Credit History: If you have a limited credit history, consider obtaining a secured loan, like a small personal loan, and repaying it diligently. This demonstrates responsible credit management.
- Dispute Errors: Regularly review your CIBIL report for any inaccuracies and promptly initiate a dispute resolution process if you find any errors.
- Avoid Frequent Loan Applications: Limit your applications for new loans or credit cards to a short period. Each application triggers a hard inquiry that can temporarily lower your score.
By following these tips and maintaining disciplined financial behavior, you can gradually improve your HDFC CIBIL score and enhance your eligibility for HDFC Bank credit cards, unlocking a wider range of financial products and opportunities.

 Written By


 Reviewed By
Last Updated: 9th September 2026
Latest from the Credit Score Blog
Get in-depth knowledge about all things related to Credit Score and your finances
What is Credit Age?
Credit Age Meaning Credit age refers to the duration for which a borrower has held credit accounts, such as loans or credit cards. It indicates how long a person has had access to and managed credit, rather than simply c
CIBIL Score vs Loan Eligibility
CIBIL Score vs Loan Eligibility: How Are They Connected? A CIBIL score is one of the factors lenders may consider when assessing a borrower’s creditworthiness and repayment history. However, the relationship between CIBI
How Often is CIBIL Score Updated?
General update frequency (monthly cycle) The earlier fortnightly reporting system was replaced with a more frequent reporting framework from 1 July 2026. Under the current RBI framework: Credit institutions must submit
How payment history affects CIBIL score
Why payment history is the biggest scoring factor Payment history is a major part of the CIBIL score, but calling it the biggest factor would be inaccurate. CIBIL identifies four main factors: payment history, credit uti
Credit History vs Credit Score
What is credit history? Credit history is the record of how a person has used and repaid credit over time. In a CIBIL report, this includes credit facilities such as home loans, auto loans, personal loans, credit cards a
Consumer CIBIL Score vs Commercial CIBIL
What is a consumer CIBIL score? A consumer CIBIL Score is a three-digit measure of an individual’s creditworthiness, based on their personal credit history, and ranges from 300 to 900. A consumer credit report records lo
What is Credit Mix
What is credit mix? A CIBIL report can contain several credit accounts, and credit mix refers to how these accounts are distributed across different borrowing categories. An asset backs secured credit; common examples in
CIBIL Score for NRI
Do NRIs have a CIBIL score? Yes, an NRI can have a CIBIL score if CIBIL member institutions in India report their credit information. This can include an Indian home loan, personal loan, credit card, or other reported cr
How to Freeze CIBIL Score?
Is a full credit freeze available in India? Yes, a full credit freeze in India is available in India, but it must be executed individually. To secure complete protection, a consumer must manually activate a freeze or loc
How to check a company CIBIL Score
What is a company CIBIL Score? The term company CIBIL Score commonly refers to a business’s CIBIL credit standing. CIBIL uses different products for businesses and individuals. A CIBIL Company Credit Report (CCR) records
Use of CIBIL score
What is a CIBIL score? A CIBIL Score is a three-digit summary of an individual’s credit history and ranges from 300 to 900. CIBIL calculates it using information in the Accounts and Inquiries sections of the CIBIL Report
Trade Credit
Trade credit meaning Trade credit is credit extended by one business to another, allowing the buyer to purchase goods or services and pay later. In simple terms, the supplier becomes the creditor, and the buyer becomes t
Methods of Credit Control by RBI
What is credit control and why does the RBI use it In the Indian banking system, credit control refers to measures that influence the volume, cost, and availability of loans and advances. The Reserve Bank of India uses m
Grameen Credit Score
What is the Grameen Credit Score? The Grameen Credit Score is designed to provide a more suitable way of evaluating the creditworthiness of people in rural areas. In simple terms, the Grameen credit score is a credit ass
Four Types of Credit
What is credit? A quick recap Credit refers to money borrowed from a lender or goods and services received from a provider with an agreement to pay later. Unlike using your own money, taking out a loan creates a repaymen

