Yes, if you operate a business/company or are a lender, you can download the Company Credit Report from the official portal of CIBIL. Also, you must have a valid membership with CIBIL to download the CCR.
- Home
- Credit Score
- Commercial Cibil Csgen
CIBIL Commercial Report : Check Complete Details on CCR

Get Your Credit Score & Report for Free, Forever!
- Instant Results
- No Hidden Fees
- Secure & Confidential
- No Impact on Your Credit Report
Get your Credit Score Report5 Lac+ people have got their Credit Scores for FREE!
+91
I agree to the Terms and Conditions of TUCIBIL and hereby provide explicit consent to share my Credit Information with Urban Money Private Limited.
Verify your number
Enter 6 Digit OTP
Change mobile number
Table of Content
Read more
A commercial CIBIL report is a type of document. It contains information about your business entity’s creditworthiness, such as CIBIL score, credit history, debt-to-income ratio, etc. When the entity’s owner applies for a business loan, the company CIBIL score is the first thing a lender may check. Whether the applicant owns a private limited company, public limited company, partnership firm, or proprietorship, the commercial CIBIL report provides the lender with a detailed insight into the company’s financial well-being and credit background. To learn more, continue to scroll down. Hereunder, Urban Money presents a comprehensive overview of commercial CIBIL. We primarily cover details such as how to get your CIBIL report, applicable features, factors affecting your company’s CIBIL score, how to improve your CIBIL score, etc.
How to Obtain Your CIBIL Commercial Report
For CIBIL commercial login, you need to follow the steps given below:
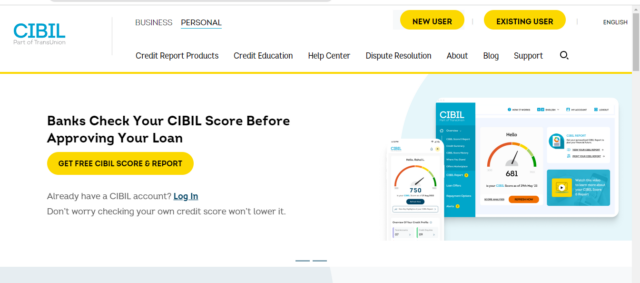
- Step 1: Visit the official website of CIBIL, a credit bureau company in India.
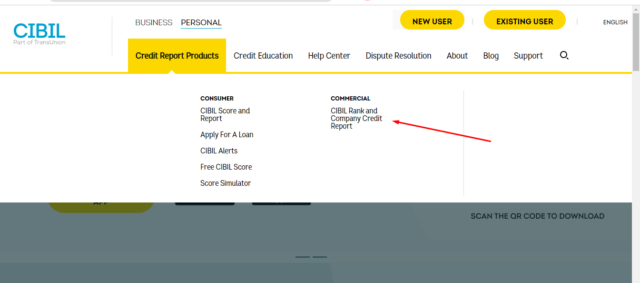
- Step 2: Go to the “Credit Report Product” menu and then select the “CIBIL Rank and Company Credit Report” option
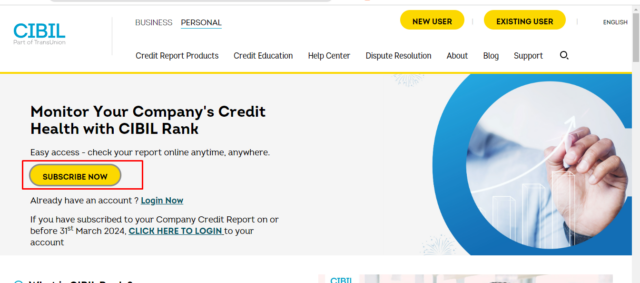
- Step 3: Tap on the “Subscribe Now” button.
- Step 4: Choose the subscription plans that best suit you, enter the company details and complete the payment.
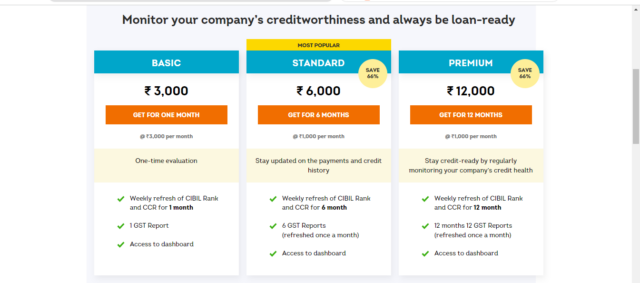
- Step 5: Complete the payment procedure and enter the company GSTIN Number
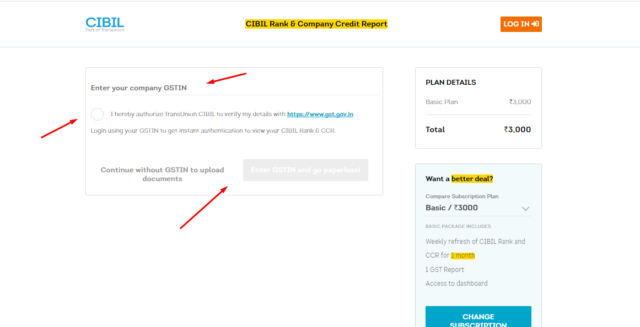
- Step 6: Upload the KYC documents and click the “Submit” button.
- Step 7: You will receive an email mentioning your transaction ID and registration ID
- Step 8: Your commercial CIBIL report will be mailed to your registered company address within a week.
Documents Required to Check CIBIL Commercial Report
Let’s examine the necessary documents you may require to check the company CIBIL score:
For Private and Public Limited Companies
If your company is registered as a private or public limited, then you have to present the following documents:
- Identity proof of one of the authorized signatories, which may include a Passport, PAN, or Driving License
- Anyone address proof from the following: passbook or bank account statement, telephone or electricity bill, sale agreement of office premises/registered lease, address proof issued by multinational or commercial banks, registration certificate issued under Shops & Establishment Act
- PAN card of the company
- A scanned copy of the board resolution along with the authorized specimen signature and signatory list
For Proprietorship
If you are a single owner of the business/company or have your business registered as a sole proprietorship; then you have to submit the following documents to check Commercial CIBIL Report:
- Proof of Identity of the proprietor, which could be a Driving License, PAN, or Passport
- Any of the following proof of address — registration certificate issued under the Shops & Establishment Act, electricity or telephone bill, etc
Note: The proprietor must self-attest all the above-mentioned documents.
For Partnership Firms
If you own a partnership firm with one or few other partners, then you must submit the following documents:
- PAN of the partnership firm
- Copy of certificate of registration or partnership deed
- Identity proof of partner requesting for the Company Credit Report, which may include Passport, Driving License, or PAN
- List of specimen signatures along with authorized signatories
Key Features of the CIBIL Commercial Report
Let’s examine the key features of the commercial CIBIL report:
- Company Background: It includes legal establishment, branches, ownership, and years of operation.
- Financial Information: It details the company’s credit standards based on financial data, such as outstanding loans, overdue, collateral, etc.
- CIBIL Rank: It reflects the company’s creditworthiness with a rank between 1 (highest) and 10.
- Credit History: It records the company’s financial history, including collections, repayments, and revenue generation.
Applicable Elements That Influence Your CIBIL Commercial Report
Here are the applicable elements that impact your company’s CIBIL score:
- Company Profile: The company profile mainly indicates the life and size of the corporation. Usually, older and bigger organisations have a well-established financial history. Therefore, they are considered more credible than startups and new businesses.
- Credit Repayment History: This refers to your repayment behaviour. Any default or late payment can significantly lower your credit score. On the other hand, paying your debt or EMI on time can enhance your overall commercial CIBIL report.
- Credit Utilisation Ratio: This is a metric represented by percentages. It signifies the difference between your total available credit limits and the amount you have utilised from that limit. Keeping your credit utilisation ratio low is considered ideal for a positive credit report, as the credit bureau company in India views this as a healthy financial habit.
- Credit Duration: This indicates the length of time you have been repaying your debt or EMI. Notably, the credit bureau in India views longer durations favourably, as they consider this a testament to responsible repayment. Thus, the longer the repayment period, the better the credit score.
- Outstanding Debts: This refers to any remaining debt you may have. Specifically, the total amount of money you must repay to be debt-free. Keeping your outstanding debt as low as possible helps improve your credit score, while higher outstanding debt can lower it.
- Credit Enquiries: This means how many credit applications you have raised. Multiple credit applications or inquiries in a short period can adversely affect your credit report. The credit bureau interprets this as credit-hungry behavior, indicating you may have experienced financial hardship.
- Industrial Sector: Specific industrial sectors have a higher risk and impact the company’s CIBIL Commercial Report. For instance, if your company operates in the oil and gas sector, deemed to have high volatility due to global market conditions, the lenders will consider your company less creditworthy compared to companies in other stable sectors like insurance and banking.
How to Improve Your CIBIL Commercial Report
Here are certain tips you can keep in mind to improve your commercial CIBIL report:
- Timely Payments: Ensure all dues are paid on time to maintain a good repayment history.
- Debt Management: Pay off debts to keep the outstanding debts feasible and your company’s repayment ability in good standing.
- Credit Utilisation: Lower your credit-to-debt ratio below 30% to maintain a balanced credit utilisation.
- Credit Enquiries: Avoid excessive hard inquiries in a short span of time, as this can indicate credit-hungry behaviour and cause a lower credit score.
- Financial Health: Maintain a long history of responsible credit behaviour and ensure your assets always exceed your liabilities.
Why Your CIBIL Commercial Report Matter
Let’s examine the importance of CIBIL commercial login:
- Loan Approval: A positive report can lead to quicker credit approvals and potentially better interest rates.
- Business Insights: It provides a comprehensive view of your business’s financial health and credit performance.
- Risk Mitigation: It helps lenders assess the level of risk associated with lending to your company.
Comparison of Commercial CIBIL vs Consumer CIBIL
Below is the comparison of commercial CIBIL and consumer CIBIL:
| Aspect | Commercial CIBIL | Consumer CIBIL |
| Target | Businesses and commercial entities | Individual consumers |
| Purpose | To assess the credit histories of business entities for loan eligibility | To assess the credit history of individuals for loan eligibility |
| Credit Model | CIBIL rank between 1 and 10 | CIBIL scores between 300 and 900 |
| Report Type | Commercial Credit Report | Credit Information Report (CIR) |
| Key Attributes | Payment history, credit mix, credit utilisation, financial stability | Number of accounts, loans, credit cards, repayment patterns |
Comparison of CIBIL Commercial Report vs Individual’s Credit Report
Below is the comparison of a company credit report and an individual Credit report:
| Aspect | CIBIL Commercial Report | Individual’s Credit Report |
| Focus | Creditworthiness and financial history of businesses | Creditworthiness of individuals |
| Aim | To evaluate credit risk and financial transactions with businesses | To evaluate credit risk with the individuals |
| Content | Business’s credit history, loan repayment, financial stability | Individual’s credit accounts, repayment history, outstanding debts |
| Scoring/Ranking | Rank between 1 (highest creditworthiness) and 10 | Score between 300 (lowest) to 900 (highest creditworthiness) |
| Analysis | A rank closer to 1 results in more favourable loan terms and interest rates | A higher score can lead to better loan terms and interest rates |
What Details Are Included in a CIBIL Business Credit Report
Following are the key details that are included in a commercial CIBIL report:
- Company Details: Company name, industry type, number of employees, legal constitution, etc.
- Contact Information: Registered office address, mobile number, telephone number, and fax numbers.
- Identification Details: Registration number, Taxpayer Identification Number (TIN), Corporate Identification Number (CIN), Service Tax Number, PAN card number, etc.
- Delinquency Reports: Financial creditworthiness of the company and guarantors, including current and past due status, outstanding amounts, etc.
How do I Rectify Information on CCR?
If the information registered on your CCR seems incorrect, you can raise a dispute with CIBIL. The portal offers an online commercial dispute form where you can provide details of the dispute, such as —
- Company Name and Registered Address
- Branch Address, if any (optional)
- Name of Authorised Signatory
- Contact details such as your phone number and email address
- Company PAN
- Report Order Number — a unique 10-digit number that reflects on the top right-hand side of your Credit Information Report (CIR)
- Date of Report
- Reason for Dispute
Click on the following link to access the dispute form — https://www.cibil.com/online/file-company-dispute.do.
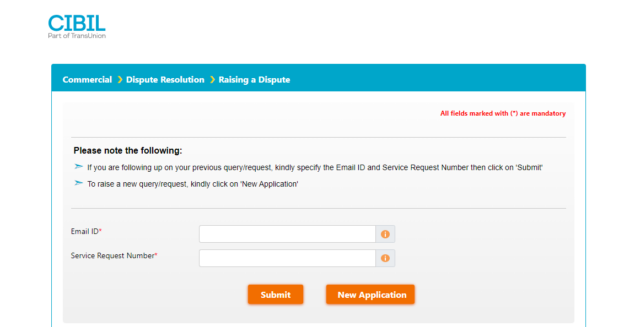
Once you have furnished the required information, enter the CAPTCHA code and click on the ‘Submit’ button.
| Related Guide |
| How is your CIBIL score calculated? |
| Written Off in CIBIL Reports |
| How to Check CIBIL Score with PAN Card |

Get your Credit Score Report worth ₹500 for FREE
5 Lac+ people have got their Credit Scores for FREE!
 Written By


 Reviewed By
Last Updated: 23rd September 2026
FAQs
Can lenders use a CIBIL commercial report to assess a business's creditworthiness?
Lenders can use a CIBIL commercial report to assess a business’s creditworthiness.
How frequently should businesses review their CIBIL commercial report?
Reviewing your CIBIL commercial report once a month is considered ideal.
Are there laws regulating CIBIL commercial reports?
The credit reporting agencies, including CIBIL, are directly regulated by the Reserve Bank of India (RBI).
Do strong CIBIL commercial reports help businesses get better financing?
Yes, having strong CIBIL commercial reports can help businesses obtain better finance and more favourable interest rates and terms.
What does Credit Order Number mean in CIBIL Commercial Report?
It’s a unique number generated every time somebody accesses your Company Credit Report from CIBIL’s database.
Who can access CIBIL rank and CCR?
CIBIL members, including financial institutions and banks, can access the CIBIL rank and CCR of any company applying for a loan.
Can I download the Company Credit Report?
Latest from the Credit Score Blog
Get in-depth knowledge about all things related to Credit Score and your finances
Oct 08, 2026
What is Credit Age?
Credit Age Meaning Credit age refers to the duration for which a borrower has held credit accounts, such as loans or credit cards. It indicates how long a person has had access to and managed credit, rather than simply c
Oct 08, 2026
CIBIL Score vs Loan Eligibility
CIBIL Score vs Loan Eligibility: How Are They Connected? A CIBIL score is one of the factors lenders may consider when assessing a borrower’s creditworthiness and repayment history. However, the relationship between CIBI
Oct 04, 2026
How Often is CIBIL Score Updated?
General update frequency (monthly cycle) The earlier fortnightly reporting system was replaced with a more frequent reporting framework from 1 July 2026. Under the current RBI framework: Credit institutions must submit
Sep 30, 2026
How payment history affects CIBIL score
Why payment history is the biggest scoring factor Payment history is a major part of the CIBIL score, but calling it the biggest factor would be inaccurate. CIBIL identifies four main factors: payment history, credit uti
Sep 30, 2026
Credit History vs Credit Score
What is credit history? Credit history is the record of how a person has used and repaid credit over time. In a CIBIL report, this includes credit facilities such as home loans, auto loans, personal loans, credit cards a
Sep 30, 2026
Consumer CIBIL Score vs Commercial CIBIL
What is a consumer CIBIL score? A consumer CIBIL Score is a three-digit measure of an individual’s creditworthiness, based on their personal credit history, and ranges from 300 to 900. A consumer credit report records lo
Sep 30, 2026
What is Credit Mix
What is credit mix? A CIBIL report can contain several credit accounts, and credit mix refers to how these accounts are distributed across different borrowing categories. An asset backs secured credit; common examples in
Sep 30, 2026
CIBIL Score for NRI
Do NRIs have a CIBIL score? Yes, an NRI can have a CIBIL score if CIBIL member institutions in India report their credit information. This can include an Indian home loan, personal loan, credit card, or other reported cr
Sep 30, 2026
How to Freeze CIBIL Score?
Is a full credit freeze available in India? Yes, a full credit freeze in India is available in India, but it must be executed individually. To secure complete protection, a consumer must manually activate a freeze or loc
Sep 30, 2026
How to check a company CIBIL Score
What is a company CIBIL Score? The term company CIBIL Score commonly refers to a business’s CIBIL credit standing. CIBIL uses different products for businesses and individuals. A CIBIL Company Credit Report (CCR) records
Sep 30, 2026
Use of CIBIL score
What is a CIBIL score? A CIBIL Score is a three-digit summary of an individual’s credit history and ranges from 300 to 900. CIBIL calculates it using information in the Accounts and Inquiries sections of the CIBIL Report
Sep 16, 2026
Trade Credit
Trade credit meaning Trade credit is credit extended by one business to another, allowing the buyer to purchase goods or services and pay later. In simple terms, the supplier becomes the creditor, and the buyer becomes t
Sep 15, 2026
Methods of Credit Control by RBI
What is credit control and why does the RBI use it In the Indian banking system, credit control refers to measures that influence the volume, cost, and availability of loans and advances. The Reserve Bank of India uses m
Sep 15, 2026
Grameen Credit Score
What is the Grameen Credit Score? The Grameen Credit Score is designed to provide a more suitable way of evaluating the creditworthiness of people in rural areas. In simple terms, the Grameen credit score is a credit ass
Sep 15, 2026
Four Types of Credit
What is credit? A quick recap Credit refers to money borrowed from a lender or goods and services received from a provider with an agreement to pay later. Unlike using your own money, taking out a loan creates a repaymen

